What To Know
- While Thailand has moved cautiously on the trade integration front, Vietnam has essentially rolled out a red carpet for global supply chains seeking an alternative to manufacturing hubs in mainland China.
- For the past thirty years, Thailand has proudly held the title of the “Detroit of Asia,” serving as a massive global hub for internal combustion engine vehicle production.
For decades, Southeast Asia’s economic hierarchy felt set in stone. Thailand, powered by its robust automotive manufacturing hubs, sprawling tourism infrastructure, and massive industrial estates, firmly established itself as the second-largest economy in the Association of Southeast Asian Nations (ASEAN), trailing only Indonesia. However, a quiet but seismic shift is reshaping the geopolitical landscape of the region. Fresh macroeconomic forecasts indicate that Vietnam’s gross domestic product (GDP) is on an aggressive track to surpass Thailand’s in nominal terms by the end of this decade. What once seemed like a distant projection has accelerated into an imminent reality, sparking intense debate among policymakers, investors, and corporate leaders across the region.
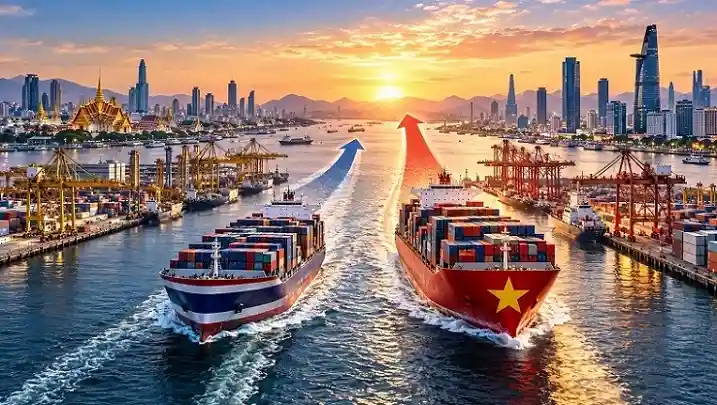
Image Credit: Bangkok Business News
As this economic rivalry intensifies, the contrast between the two nations’ growth trajectories has become impossible to ignore. Here at Bangkok Business News, analysts tracking these shifting regional dynamics note that the coming years will serve as a definitive turning point for Southeast Asian commerce. While the World Bank recently upgraded Thailand’s 2026 growth forecast to a modest 2.0 percent, Vietnam continues to expand at a staggering pace, consistently posting annual growth rates between 6 and 7 percent. This widening growth differential is setting the stage for what economists call “The 2030 Flip,” a milestone that will reshape trade routes, corporate investments, and employment landscapes across both Hanoi and Bangkok.
The Math Behind the Mirror: Analyzing the Trajectories
To understand how Vietnam closed a multi-billion-dollar gap so quickly, one must look at the structural math of both economies. Thailand’s economic engine is facing a classic middle-income trap compounded by severe demographic headwinds. The country has officially entered an aged society phase, meaning its workforce is shrinking just as its productivity gains have begun to plateau. A low birth rate, combined with a highly indebted household sector, has suppressed domestic consumption and constrained local manufacturing innovation.
In sharp contrast, Vietnam is riding the crest of a golden demographic wave. More than half of its population is under the age of 35, providing an energetic, highly adaptable, and cost-effective labor force that international corporations crave. Furthermore, Vietnam’s aggressive pursuit of high-standard multilateral trade agreements—such as the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) and the EU-Vietnam Free Trade Agreement (EVFTA)—has given it unparalleled market access. While Thailand has moved cautiously on the trade integration front, Vietnam has essentially rolled out a red carpet for global supply chains seeking an alternative to manufacturing hubs in mainland China.
The Silicon Shield vs. The Automotive Hub
The battleground for economic supremacy is most visible in the manufacturing sector. For the past thirty years, Thailand has proudly held the title of the “Detroit of Asia,” serving as a massive global hub for internal combustion engine vehicle production. However, as the global automotive industry undergoes a rapid, disruptive pivot toward electric vehicles (EVs), Thailand’s traditional supply chains are under immense pressure to adapt. While the Thai government has successfully courted several major Chinese EV manufacturers to set up local operations, the transition has disrupted the established ecosystem of local auto-parts suppliers.
Meanwhile, Vietnam has skipped a generation of industrial development to build what analysts call a “silicon shield.” It has rapidly transformed itself into a global electronics powerhouse. Tech giants like Samsung, Intel, Foxconn, and Apple suppliers have poured billions of dollars into high-tech manufacturing plants in northern Vietnam. Samsung alone produces nearly half of its global smartphones in the country. Because the margins, scaling capabilities, and global demand for high-end electronics and semiconductors currently outpace traditional industrial manufacturing, Vietnam’s export values have surged dramatically, allowing its nominal GDP numbers to rapidly catch up to Thailand’s.
Foreign Direct Investment: Where the Money Flows
Foreign direct investment (FDI) serves as the ultimate leading indicator of a country’s future economic health, and the current flow charts tell a definitive story. For several consecutive quarters, Vietnam has outpaced Thailand in attracting realized FDI. Global venture capital firms and multinational corporations no longer view Vietnam merely as a low-cost clothing and textile exporter; they view it as the primary beneficiary of the global “China Plus One” strategy.
This shift is not merely about cheaper labor. Vietnam has invested heavily in physical infrastructure, rapidly expanding its deep-sea ports, constructing massive highway networks, and upgrading industrial parks to meet Western environmental, social, and governance (ESG) standards. Thailand, while possessing highly sophisticated infrastructure along its Eastern Economic Corridor (EEC), has struggled with political fragmentation and bureaucratic delays that have slowed down mega-projects. For a foreign board of directors deciding where to anchor a twenty-year industrial investment, Vietnam’s policy continuity and aggressive pro-business stance frequently tip the scales in its favor.
What “The 2030 Flip” Means for Local Jobs
For the average citizen in Bangkok, this macroeconomic race is not just an abstract data point on a chart—it directly impacts career trajectories and wage growth. As Vietnam’s GDP overtakes Thailand’s, the region’s talent ecosystem will shift. Historically, Bangkok has acted as the undisputed regional corporate headquarters for multinationals operating in mainland Southeast Asia. The city’s world-class retail, international schools, and premium real estate made it an easy sell for expatriate executives.
However, as the economic center of gravity tilts toward Hanoi and Ho Chi Minh City, corporate budgets will inevitably follow. We are already seeing regional marketing, logistics, and operational roles migrate eastward. For Thai professionals, especially those entering the tech, finance, and advanced engineering sectors, the slowdown in local GDP growth means stiffer competition for a shrinking pool of high-paying corporate roles. Conversely, it creates pressure on Thai enterprises to upgrade their workforce skills, improve English language proficiency, and aggressively adopt automation to remain competitive against their highly driven Vietnamese counterparts.
Wake-Up Call for Bangkok’s Corporate Giants
This imminent milestone serves as a massive wake-up call for Thailand’s established conglomerates. For generations, a handful of multi-billion-dollar Thai family businesses have dominated domestic retail, agriculture, energy, and real estate. These corporate giants have traditionally enjoyed high barriers to entry at home, but a stagnant domestic market is forcing them to look outward.
Interestingly, the response from Bangkok’s corporate boardrooms has not been to retreat, but to invest heavily in the very market threatening to overtake them. Major Thai retail networks, energy firms, and petrochemical giants have deployed billions of dollars in acquisition capital directly into Vietnam’s consumer and renewable energy sectors. In a twist of economic irony, the growth of many of Thailand’s largest companies is now being fueled by the booming Vietnamese consumer class.
The Final Sprint to 2030
The economic race between Thailand and Vietnam is far from a foregone conclusion, but the momentum is undeniable. To maintain its crown, Thailand must rapidly execute structural reforms. This includes aggressively tackling its massive household debt crisis, fast-tracking free trade negotiations, and overhauling its educational system to meet the demands of a digital economy. The country cannot rely on the economic playbooks of the 1990s to solve the challenges of the 2030s.
Vietnam, too, faces hurdles, including the need to transition from low-value assembly to genuine high-tech research and development, alongside managing an energy grid under intense strain from rapid industrialization. Yet, as the clock ticks closer to 2030, the gap is closing to a razor-thin margin. The nation that manages its structural challenges more effectively will emerge as the true economic anchor of mainland Southeast Asia.


